Showing posts with label inflation. Show all posts

Wednesday, March 26, 2014

After QE; Piketty and neo-feudalism

There is a lot of nonsense going around about interest rates going up post-QE. Following John Hussman's lead, in a recent post I showed the empirical regularity governing the relationship between central bank balance sheet as a percent of GDP and long-term interest rates proxied by the 10 year T-bond.

Recently Base/GDP has been about 0.22, so we are way out on the right end tail. It would take a reduction of the ratio of about 15 percent of GDP to begin to raise long rates, or about $2.6 trillion at current rates of GDP. The St. Louis base is currently at $3.7 trillion, and has been growing at over 20 percent a year since the last recession.
Now, "tapering" is a reduction in the rate of increase of additions to the base, not a reduction of the base. The chart looks to me like a very strong empirical regularity indeed. So the chance that long rates will rise anytime soon is remote in the extreme, as the Fed has no announced plans whatsoever to actually reduce the base.
Long rates will remain low and the bad debt clogging the banking system will remain impacted, that much seems assured for years to come.
What is a somewhat lower probability outcome is that the dump-the-dollar movement internationally gains sufficient momentum that the Fed has to buy up more and more (perhaps virtually all) new Government debt. This might be called the MMT-by-force-majeure outcome, as there is little chance that such additions to the Fed's balance sheet will ever go away.

In this latter case rates will not go up because of the empirical regularity shown above, but as the dollar falls on the foreign exchange markets due to weak demand to hold or trade in dollars, there will be import inflation domestically in the US. This will cause a further collapse of effective demand--already afflicting the bottom 80 percent or so of Americans--as real purchasing power of consumers is decimated. The US will become an even less attractive place to invest, and capital flight will occur. The US's status as a banana republic will be cemented.

This is the essence of the dreaded global currency reset: the dollar falls on international markets, import inflation slams domestic real demand, but neither short-term nor long-term interest rates rise (short rates exhibit a similar empirical regularity to that shown above). A domestic stagflation occurs. The Fed, ever the servant of Capital, will fight the inflation with modest rises in short rates (this can be done administratively in the short run) sufficient to beat any thought of asking for higher wages out of the heads of workers even though labor cost-push inflation exists only as a curiosity in economic history textbooks.
In the final chapter plutocrats of various "nationalities" (with allegiance to none) will divvy up Plantation America, keeping the best parts of it private, for themselves and their would-be-royal progeny.

Enter the Anti-Mainstream Economist

Certainly Thomas Piketty is the most important economist of the past 80 years, since the last Fourth Turning (Keynes got it that time). I highly recommend The New Yorker's review of his big book (here). A Frenchman, Picketty came to the US at 22 as a young economics superstar and to his great credit, became immediately disenchanted (disgusted is a better word, probably) with the status-quo-supporting mathematical fictions he encountered at MIT. (Disgust afflicted your correspondent upon entering economics at the graduate level in search of "science" after an undergraduate career studying literature.) Son of a leftist French couple, Piketty imbibed the Marxist notion of capital increasingly displacing labor leading to the reserve army of the unemployed and set out to study the issue of the distribution empirically, probably sensing that only real world data could displace the mathematical fictions of the self-congratulating, narcissistic mathematical economist-priests ruling policy in the West.

Piketty's concerns over where the world is going are as dire as mine. He is the Anti-Mainstream economist on the white horse that I thought could never possibly arrive. The New Yorker disappointingly pooh-poohs Piketty's suggestions that we need to raise taxes on the incomes and wealth of the plutocrats as politically infeasible. (But of course The New Yorker’s readership inhabits the status quo, so what else could they say?)
Democracy will have to be reborn to prevent a return to out-and-out feudalism.
It couldn't happen here, of course (although Piketty now has a stateside ally in fellow French-born Berkeley economist Emanuel Saez). Piketty turned tail after a couple of years in the US and returned to Paris, where he has remained since.

[Editor: spelling of Piketty's name corrected 3/27/2014]

Thursday, March 20, 2014

Fiat money = funny money => Fed must screw labor

h/t Mish for pointing out an article by Adair Turner, former Chairman of the United Kingdom’s Financial Services Authority, a member of the UK’s Financial Policy Committee and the House of Lords, suggesting that the Fed or any fiat money central bank might accept conversion of assets on its balance sheet, i.e., Treasuries, into zero coupon perpetuities, and so create "helicopter money" and permanent monetization of the sovereign debt.

I suggested just this strategy as a joke some time ago (here).

However, we all knew that the Fed can and does print money. But stating it as baldly as this brings me back to the problem this causes in the labor market.

As I have said repeatedly, inflation (a sustained wage price spiral inflation) is always and everywhere a labor market phenomenon accommodated by monetary policy.

Thus, with the vast overhang of base the Fed must worry about inflation in the long run, even if not so much right now. Why not now? Because prosumers are overburdened with debt and inflation is nowhere raising its ugly head. Looking more deflationary now, it is.

But should actual deleveraging take place by some other means than a few bad debts actually being charged off (imagine that!), such as bad debts being recognized as such (FAS 157 thrown out, good riddance) and debtors finding relief as the (unpaid) debts hit statute of limitation dates with no more recourse--then the Fed would have to worry about a wage-price spiral getting going.

In other words, the Fed is intrinsically anti-labor and always will be. What did Paul Volcker teach us, if not that? You got to recruit some cannon fodder, some inflation fighters to win the war on inflation.

There's an interesting wrinkle in here in that Janet Yellen has allegedly stated her desire to see the labor force participation rate improve, while at the same time worrying that it will adversely impact the unemployment rate (duh!) and hence, confidence. (My readership is small but highly intelligent and knows that if discouraged workers are included the unemployment rate is well above 10 percent by the governement's own questionable figures.)

I do believe the Fed economists are aware of the psychological importance of the unemployment rate that the unknown economist whose work I channel has established, and which the econophysicists seem to appreciate far more than the professional economist (i.e., generally establishment cheerleaders) community does.

Sometime within the next few years the unemployment rate will meet its falling adaptation level and rise above it. That is when we will see the next collapse of confidence. So the model predicts.

In passing I note that MMT does not really offer a way out of the wage price spiral problem. They just seem to be willing to inflate the debt out, disco style. However, the danger of hyperinflation may be greater this time, given the size of the base, and they seem oblivious (to me) to the Austrian distributional implications that those who get new money first can increase their wealth at rates much faster than those depending on increasing real wages can expect.

To bing this discussion full circle, let's ask what comes next for the international monetary system? Does an IMF ADR basket currency make the central banks love labor any more? I think not. Unless they're playing competitive devaluation games, they still can't afford too much inflation ("a little inflation is a good thing, but not too much"--this is the mainstream cant).

Given the plutocratic distribution in the world today, it seems to me that any fiat money system broadly adopted is going to result in labor continually getting screwed, absent really aggressive incomes policies (guaranteed basic income and health care, for example; or even better, enforced limits on wage contours, now being challenged even in Sweden, such is the prevalence of greed in the current historical moment).

History shows that a metal based system achieves stable prices over long periods. Sorry, "Rich Dad, Poor Dad," you're not a genius for investing in real estate. To paraphrase Paul Samuelson, during an inflation every fool is a great financier. It takes no brains to load up on debt when inflation is guaranteed.

Are there financial crises under a metal standard? Yes, just like under fiat banking as it rides into its sunset. The answer to cyclical variations is always to let them happen, to concentrate on stabilizing people and not "the business cycle," to take care of displaced persons during the adjustment. And to keep banks out of the business of speculation with other people's money.


Sunday, March 9, 2014

The Ukraine: the dollar's Waterloo?

Very trenchant analysis from www.thegoldenjackass.com:

The desperation of the Anglo-American leadership, guided by the steady corrupt banker hands, has never been more acutely high, nor obvious in full view. The entire Ukraine situation is a travesty. It includes Langley agents killing police and street demonstrators from rooftops, the confirmation coming from the Estonian Embassy (translation of scripts). It includes thefts of official Ukrainian Govt funds, again sent to the Swiss hill sanctuary. It includes sanctions delivered by a US Paper Tiger, sure to cause horrific backlash. It involves the last gasp attempt to obstruct the Gazprom energy pipelines, which will inevitably corner the European market in monopoly. It involves subterfuge with the NATO card (aka Narcotics And Treachery Outlaws) with missiles placed on the Russian borders. Look for NATO members to find a back door to exit the spurious treaty. It involves playing with nitro-glycerine in the Petro-Dollar room. It involves putting tremendous risk for much more clear isolation of the United States. The more the USGovt pushes, the more the US will be isolated. Remember that Nazis steal from their enemy states, de-fraud from their allied states, and force themselves into an isolated state. In Ukraine, the United States has over-played its weak hand. Already, a secret document was leaked in London that the UKGovt would not support the US-led sanctions against Russia.

History repeats itself from the Kremlin phone calls made during the Syrian conflict just a few months ago, when the UKGovt withdrew its support and left the US isolated, looking very weak. Already, Putin has threatened to dump USTreasury Bonds. Putin aptly calls the Anglo-Americans as Mutants. Imagine the lunacy of trying to cut off the only Russian warm water military naval port in the Crimea. Just as stupid as the Trans Pacific Partnership faux pas, trying to cut off China from its Asian neighbors and partners in trade. The intelligence level of the USGovt has never been more stupid, destructive, and in full view. The lost ground for the United States is obvious and glaring in the Persian Gulf, the Mediterranean Sea, and the Caucasus region.

IMMEDIATE PETRO-DOLLAR RISK

If the Kremlin demands Gold bullion (or even Russian Rubles) for oil payments, then the interventions to subvert the Ruble currency by the London and Wall Street houses will backfire and blow up in the bankster faces. Expect any surplus Rubles would be converted quickly to Gold bullion. If the Chinese demand that they are permitted to pay for oil shipments in Yuan currency, then the entire Petro-Dollar platform will be subjected to sledge hammers and wrecking balls. The new Petro-Yuan defacto standard will have been launched from the Shanghai outpost. If the Saudis curry favor to the Russians and Chinese by accepting non-USDollar payments for oil shipments, then the Petro-Dollar is dead and buried. The rise of the Nat Gas Coop run by Gazprom is in progress, its gas pipelines to strangle the OPEC and its bastard Petro-Dollar child. The entire USDollar foundation with the USTreasury Bond bank reserve structure is at risk is collapsing, as consequence to the desperate adventure and criminal activity conducted in Ukraine. Just like with Syria, a hidden giant energy deposit is concealed under the table. Off the Lebanese and Syrian coast, a massive off-shore energy deposit was recently discovered. The US & UK & Israeli oligarchs wish to take it all. Confusion is their game. In the western plains of Ukraine, a massive gas deposit was recently discovered. The US & European oligarchs wish to take it all. Confusion is their game.

The danger level has never been higher. No resolution to the Global Monetary War can come, which we have been seeking, without a climax. It is hardly just a financial crisis amidst a stubborn economic recovery. The nature of the currencies and their underlying sovereign bond foundation is highly toxic, which requires a strong replacement as solution, using an alternative to the USDollar alongside its reserve ledger item the USTreasury Bond. A return to the Gold Standard is coming, but the birth will have loud pangs and possibly broad damage suffered. The Global Currency Reset is better named the Return to the Gold Standard. The United States and London will not give up their control of the Weimar Printing Press easily, used for elite self-dole of extreme wealth. It has served well as the Elite credit card. They will not go quietly, and assume their place in the backwater without taking the world to the brink. No climax can occur without enormous risk and loss. The Global Paradigm Shift is in full gear, with attendant risk huge here and now. My Jackass firm belief is that the US/UK fascist team face a Waterloo event in Ukraine, the victim to be the Imperial Dollar. This bulletin will not be a comprehensive note, as the situation is too vast. The information in the Hat Trick Letter is used to interweave a story of the impending removal of the USDollar from its corrupt throne.

UNITED STATES TRAPPED AND CORNERED

The Anglo Americans have fallen into a carefully designed trap by the Russians and Chinese in a clever designed sequence. More Sun Tzu tactics have been put into practice, which utilize the momentum from the enemy to be thrust back on them. Planning for final steps must have taken place during high level Putin meetings with Xi from the elite Sochi viewing box. The unfolding of events has been more carefully engineered and orchestrated than what appears. The US/UK team has been caught in a vise for months, as the rejection of the USDollar as global reserve currency is in high gear, the refusal of the USTBond a recognized trend in diversifications. The death process is slow and grueling. Much of the American Hemisphere is surrounded and controlled by Russia & China, whether the canal, the port facilities, the oil supply, the mineral deposits, even Yuan Swap facilities. Africa has largely gone under Chinese control, with Russia playing a hidden role as well.

The Persian Gulf is in transition, with the critical protectorate role shifting to China. The Qatar royals have just ordered a dismissal of USGovt ambassadors from their nation. Note that Qatar is the site of a giant USNaval base. To be sure, the Sochi Olympic Games are over, a successful event. The gloves have thus come off. The risks have reached acute levels. The US leadership seems cavalier to the risks that over half the USGovt debt is in foreign hands, over 30% of it in Russian & Chinese hands. A severe backlash cometh. The most vulnerable player in the room is the most aggressive, arrogant, vile, and obnoxious. The instability of the situation is far beyond acute. The victim will be the USDollar and its sidekick the USTreasury Bond. The USTBonds will be kicked out of the global banking system. The Third World awaits the United States, for its domestic betrayals, its financial failures, its criminal deeds, and its war aggression.

THE RUSSIAN BACKLASH TO BE SUDDEN

Russian President Vladimir Putin will slam the West, and very soon. The initial salvo might be a natural gas cutoff by Gazprom, the Russian giant which has fast moved into the global monopoly position. Eventually, Putin might demand gold payment for the natgas in the captured pipelines, that being the plan according to The Voice. Russia supplies one quarter of Western European gas needs. It will be the opening salvo for Gold Trade Settlement, for which the Iran workarounds to the sanctions provided the critical prototype. Combined with a formal announcement of USTreasury Bond sales in volume by Russia & China, the impact would be tremendous, even devastating. The reverberation will be soon seen as the pending demise of the defacto Petro-Dollar Standard, dictated by crude oil sales in USD terms. It will also be soon seen as the end of the USTBond as the global reserve standard in banking systems. Notice for over two years, the primary buyer of USGovt debt (and its refunded rollover) has been the US Federal Reserve via bond monetization, an absolute heresy to central banking. Hyper monetary inflation cannot stand as fixed policy. The world has responded by constructing an alternative to trade settlement. The forum has been the BRICS conferences and the G-20 Meetings of finance ministers. The US & UK will gradually be excluded from both forums, a process well along. Even traditional allies like Japan are buying gold in high volume, with suppressed lowball data so far. This is game over for the USDollar, the direct victim of Ukraine backlash. The war against Russia has been veiled, but the Jackass has exposed it.

VEILED ATTACKS AGAINST RUSSIAN GAZPROM

First was the attack against Russian Gazprom in Cyprus. It was a hidden attack made to look like a bank confiscation event. Notice no bank account confiscations outside the small but important island nation. The entire Russian banking clearance system had been done through Cyprus. Also, Russia was making significant transactions to purchase Gold bullion using Cyprus as clearing house for the purchases. Second was the attack against Russian Gazprom in Syria, another complicated event. The US had used the Libyan Embassy as a weapons running facility (major diplomatic violation), after which the US lost Egypt as a transfer station on the weapons running. The false flag attack in Syria was made to look like a chemical weapons event. However, the Saudis were the guilty party. The motive by the US was to block the advance of Russian Gazprom pipelines, which are to connect to the vast Iran supply centers. Iran has far more oil & gas than Iraq. In fact, Iran is the linchpin nation, which will throw its support toward Russia. Iran will push the Nat Gas Coop certain to eclipse Saudi Arabia and the loud gaggle of OPEC members. With the Russian Gazprom, together Iran and the Nat Gas Coop will usher in the Petro-Yuan Standard and bury the Petro-Dollar, the price set by Russia, the contracts set in Shanghai. Thus the Saudis will be expendable, and their Gold in London to be totally stolen.

Move to the present. Third was the attack against Russia Gazprom in Ukraine, done by the CIA and its partner security agents from the small ally nation on the SouthEast Med corner. The old game of destabilization, popular uprising, bank thefts, and now data files stolen has been put into action. The theft of significant funds in Ukraine has only started, funds gone to Swiss banks. The full betrayal will be seen soon. The US & UK have a lunatic plan to corral the Ukraine pipelines and possibly the vast farmlands of Ukraine. The wrong-footed plan will backfire, when Putin cuts off the natgas supply to Europe, when Putin demands a new type of energy supply payment structure, and when Putin engineers certain other steps. They might execute a Nat Gas Coop double in price, much like the OPEC event in 1973. Witness the upcoming Birth of the Eurasian Trade Zone, the birth pangs heard in Ukraine. The United States and Great Britain will not be included. The Eurasian Trade Zone will span 14 time zones and will settle in gold.

IRAN WORKAROUND AS KEY PROTOTYPE SOLUTION

The Anglo Americans have disrupted a key nation with longstanding historical and religious ties to Russia. The land of Ukraine also contains Russia's only warm water naval port in the Crimea, the site of a recent suspicious earthquake. The response will be swift and firm. The Eastern nations (led by China & Russia) have been making detailed preparations in the last couple years to launch the alternative trade system founded in Gold Settlement. Its launch lacks a potential open door trigger, possibly offered by the Ukraine situation. The Gold Standard could return in a baptism by fire. The open door trigger appears to be the Western interventions into Ukraine, since the Western banking structures will not be permitted to collapse, the ugly reality. The abuse of the central bank monetary expansion and fraudulent bond redemption has gone totally out of control, forcing an endless cycle of alternative preparations and motivated reactions, including the Iran workaround with Turkey as intermediary in gold provision. Other attacks have taken place in the last few months against the Russian Ruble by Wall Street firms. The reaction will possibly be the launch of what could eventually be understood to be a gold-backed Ruble currency, combined with natgas cutoffs to Europe and USTBond dumps. At first it could be perceived as the oil-backed Ruble, but its quick hidden conversion to Gold bullion could be revealed later on. The USDollar will be discarded as obsolete, even toxic. The USDollar debt basis might be widely accepted to be the cause of the global financial crisis, and the USFed Quantitative Easing be widely understood to be the cause of the global financial collapse.

EUROPE AS KEY REGION TO TIP EASTWARD

Events inside Western Europe could unfold rapidly. Behind the scenes, much is happening. The important German-French Axis is breaking down, weakened by each passing month and bailout exercise. The motive for much of the German support of bailouts and rescue plans, as faulty as they have been, is the oversized German ownership of both French Govt debt and big French banks. They will fail, both the French sovereign debt and the big French banks. Germany must undergo a split, with a restructure from the devastating damage due to Southern European sovereign debt and related big bank losses. At the same time, Germany is on the verge of turning East to Russia. Already Russia is a large energy and mineral supplier to Germany, the heavy railway facilities in place. The core of Nordic Europe is firm. Austria and Finland are aligned with the pragmatic forces in Germany and the Netherlands. Italy is being transformed, but Spain might be lost to chaos. Turkey is also undergoing change during chaotic reform. The entire NATO Alliance has never been weaker. The military action in Ukraine is framed as a supposed NATO exercise to honor a treaty. Watch the loose end like Turkey fall off the NATO wagon, while Finland falls off the Euro currency wagon. The Jackass is eager to see the Snowden NSA files reveal key data on the illicit usage of NATO bases for narcotics distribution, the origin being Afghanistan. What a bombshell it would be if Turkey announced that their government would no longer permit heroin shipments from USMilitary aircraft on their Incirlik Airbase.

A key player in the mix is Israel. They have a Tamar floating platform, whose natgas has been pledged under contract to Russian Gazprom. The tiny nation is possibly changing its alliances out of pragmatism, seeing its drained weakened host that has duly served its purpose. The next big step is for Western Ukraine to suffer the drain of remaining resources (financial and agricultural) to the West, using all the diplomatic tools the Euro Elite can muster. The people in the East will realize that they have been betrayed once more by the Western powers. This is the critical final step. Several swing nations will consequently align with Germany, if only to make being integrated by Russia less painful. During all the transitions, China will take care of Asia in this game. The remaining overriding question is whether the US & Britain will go quietly in the night of faded empires, or else to wreck the world with nukes and viruses. The main exports out of the United States and its royal handlers have been fraudulent bonds, military hardware, genetically modified food, fast food with diabetes, pharmaceuticals, surveillance software, computer viruses, and jamming software technology. Such is the nature of the fascist transformation.

RUSSIA CANNOT BE ISOLATED

The West is in for a gigantic surprise in the sequence of events to unfold. They have placed criminal oligarchs into top government positions in Ukraine. Doing so might suit the West but not the Ukrainian people. The political brain trust in Berlin shows extremely errant strategy, still kowtowing to the USGovt and London Elite in an incomprehensible manner. The West cannot isolate Russia, which is the latest absurd bone-headed strategy. They need Russia in vital ways that will become apparent when the West faces energy supply cutoff or forced Gold payments during an open global USDollar rejection. The US will quickly feel the lost Petro-Dollar gear mechanisms. China has already aligned itself beside Russia, which makes isolation impossible. Consider the Russian commodity supply and Chinese industrial power, the new axis to the Eurasian Trade Zone.

The West cannot continue to bully Russia & China. Poking a stick in the bear's face will not work for long. Disrespecting the Chinese creditor is deep folly. The risk that coincides is for the two Asian superpowers to threaten or actually execute a dumping initiative of USTreasury Bonds, and force the United States to use its last card in a grotesque display of hugely amplified monetary expansion. The US would collapse by falling on its own sword, the event occurring in the Weimar chamber. A super high volume bond monetization machine to cover globally dumped USTBonds is a strong likelihood as climax event, with a broken derivative mechanism that is revealed during its fracture. The London banker murders (another Jackass correct forecast, made in mid-2011) indicate a motive to keep covered up the extreme $100 billion JPMorgan derivative losses at the hands of the London Whale Bruno Iksil, first sighted in May 2012. The accelerated hyper monetary inflation in response to Russian & Chinese joint retaliation would finally kill the USDollar. The echo event, born from failure, would be for the USGovt to launch the new split Scheiss Dollar. Then the USGovt could have its domestic currency finally, and then wreck it with an assured painful sequence of devaluations. The fundamentals for the US domestic only currency are truly horrible, typical of a Third World nation. Ukraine is about the last gasp of the USDollar. It has no viable defense.

UKRAINE AS WATERLOO FOR THE USDOLLAR

Ukraine is the Waterloo event for Team Obama and the Wall Street handlers, the true controllers of the White House puppet. Ukraine will lead to wreckage to the USDollar and its USTBond partner in crime. Witness the death of the USDollar and the Birth of both the Gold Trade Standard, on the new Eurasian Trade Zone landscape. Neither Russia nor China will cooperate on the IMF super sovereign reformed currency basket at this point, not during extreme hostility and conflict. Hope and pray for cooler heads to prevail, since already many serious military attacks have occurred with advanced weapons off the Syrian coast. The Western Press prefers to frame the Ukraine situation as one more curious Orange Revolution event staged in Eastern Europe, akin to the other deceptive Arab Spring events. The old Soviet Union was trapped years ago, forced to use hyper monetary inflation in defense, as the nation imploded financially. The United States is now trapped in an ironic parallel manner, and will be exposed for its heretic inflationary response that ramps up to obscene volumes, followed by financial implosion. In fact, the events from here onward are the final hurrah for the USDollar regime and the criminal cabal.

Now has never been a better time to own a big stack of gold & silver coins & bars, stored in a secure place outside the United States, outside England, outside Switzerland, even outside Canada. The people must defend against a climax of systemic failure, led by arrogance, stupidity, desperation, and delusion, even armed aggression. It remains to be seen whether the Kremlin has some secret allies who might emerge in time, from other worlds. But that is an entire other story to be told someday maybe. We earthlings will all find out soon enough. Times are changing fast, and better to be alert than to get hurt. The Global Currency Reset lies directly ahead, complete with its doubled Gold price and doubled Silver price. The Russians & Chinese are motivated to respond to a military prod, poke, and nudge by delivering a financial response. The rejection of the USDollar is near. The rapid diversification away from the USTreasury Bond is near. The arrival of the new Global Gold Standard is imminent.


Tuesday, January 14, 2014

Global currency reset: is it real?

The Intertubes are buzzing with talk of a global currency reset, usually in conjunction with a sale of a DVD that the seller alleges contains secrets that "the elite" have imparted to him that will make the difference between survival and adject ruin in your life. The most cogent of these is by Pastor Lindsey Williams here.

The basic argument is that Christine Lagarde has secured agreement from some 204 nations to enter into a new managed float currency system that, however, will move currencies toward new exchange rates based on national "assets." America, being the premier debtor nation in the world, would be devalued in its new channel, especially relative to the yuan. This of course is what a lot of people would like to see happen to stimulate exports. This system is allegedly to be kicked off by the end of first quarter 2014. There will be some sort of gold-backed or basket-based new international reserve currency introduced.

Obviously America is hit by stagflation as goods from China increase in price by 30 percent or so. Simultaneously the government in 2014 or 2015 will seize 30 to 50 percent of public and private pension funds to pay down government debt.

I have little doubt that the dollar's reserve currency status is weakening. Many significant trade deals have been recast in the past few years out of dollars into other currencies, or in some cases, into commodities. But if such negotiations for a global currency reset have taken place they have been kept very quiet.

The problem I have with this story is that it conflicts with what I see as the most likely outcome, the credit supernova, in which all countries succumb to temptation to beggar the rest of the world to inflate out their debt and depreciate their currency. America's dominance and relative safety (note the negative yields on recent T-bill auctions) would seem to augur a relatively strong dollar in such a supernova scenario.

However, Williams does make a credible case that the American economy will totally collapse in 2015 when the business mandate of Obamacare takes effect. The press has recently given coverage to the profit guarantees that the health insurance companies enjoy under Obamacare. Recent retail sales numbers certainly suggest a collapse of demand (see this).

The good pastor also maintains that the smart meters that have supposedly been put on most American houses are in fact microwave mind control devices that have softened up the population for the imposition of the totalitarian new world order without violent resistence (this seems to entirely based on the allegations of one Barrie Trower, a British physicist).

What economists call "effective" demand collapses when most people's incomes are falling, even if total income (GDP) is ostensibly rising. The rich just don't spend enough or on the right things to keep the circular flow going in a healthy way. And when the most attractive investment opportunities are offshore, anyone with a mutual fund can send their capital abroad. Add to this the bad debts of the banks that they have transferred onto the backs of the American (and Irish, and Spanish, and Portuguese...) people and the stage is indeed set for collapse. The question will be whether the rich will push the poor into a die-off (life expectancies are already declining among the lower classes in America, and probably elsewhere) or whether the population of the world will learn to share in the context of a just society.

In any event, we'll see if there's anything to all the fevered talk about the "global currency reset" within 90 days.


Sunday, October 20, 2013

My favorite blog posts from the week

Tax Rates, Inequality, and US Deficits – Barry Ritholtz.  Sometimes no one nails it like Barry.

Its Friday, after what was for me a long and annoying 17 days. But the shutdown is over, US markets are at all time highs, and Bob Shiller got his Nobel (more on this tomorrow).

You might think that I would be at peace with the current state of the world, but life is never that simple. You see, I have assumed the task of explaining things which require explaining. By some quirk of fate and an odd academic background, I find myself with skills in simplifying complex matters. Whether OCD or over-compensation for some other defect, this is my lot in life. (I made peace with it long ago).

As we discussed yesterday, amongst all of the background nonsense since October 1, the noise about the deficits was not really about budget deficits at all. Rather, it was about a decidedly narrow ideology held by a small percentage of Americans. Their belief is that government should be much smaller. This is a legitimate political ideology, one that has persisted over the centuries.

Their approach to this philosophy, however, is far less intellectually honest. Rather than having a full on debate on that subject — a debate they are likely to lose — they have chosen a very different approach. This time around, they made the deficit a proxy.

Because of what I do for a living, I found this offensive. Deficits impact fixed income, an important part of portfolio planning. They impact available credit, capital for investment, in a broad and varied way. Hence, the deficit is a genuine issue, a real problem that should be addressed in a mature and responsible way. It can be easily solved using intelligent solutions, but for the ideologues in Washington DC (and elsewhere) who refuse to treat it as the basic mathematics and accounting problem it actually is. The way the Tea Party and others have treated the deficit reminds me of the approach Meredith Whitney took to Municipal Debt. Both groups are stunningly ignorant about their subjects, while possessing the skills to allow them to exploit the topic, hog the spotlight for themselves and other tangential pet issues.

The Tea Party, like Whitney, turned an important question of debt and credit and solvency into one giant PR clusterfuck.

Back to our issue of taxes (next week, I will address spending). Amongst Industrialized Nations, the United States has amongst the lowest tax rates in the world, especially for those folks (like myself) who reside at the top of the income scale.

To demonstrate this, I want to point to the IMF’s World Economic and Financial Surveys: Taxing Times. It is chock full f great charts and data and other interesting results of the IMF survey.

The two below caught my eye. They are rather instructive for our discussion of taxes and deficits in the US.

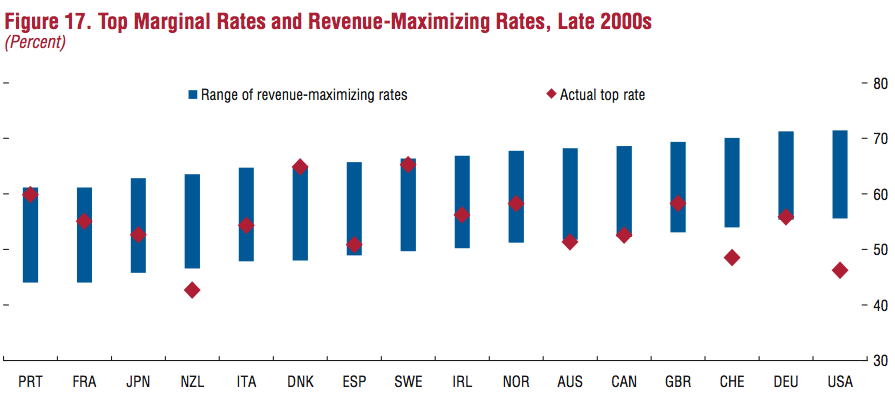
The first looks at major industrial nations, and compares what the IMF calls their Revenue-Maximizing Tax Rates (blue line) versus their actual top rate (red dot).

As you can see, some countries — Denmark and Sweden — are at the top of the revenue maximizing ranges. Other countries — Canada and Germany — are at the bottom of their revenue maximizing ranges.

Then there is the United States, which is simply far off the scale, way below the bottom of its revenue maximizing range.

If your concern is deficits, than you must take notice of how much money the USA is leaving on the table. I am not suggesting that the role of government should be to maximize their tax revenues, but rather to suggest that if you want to close the deficit, you need to at least be in a defendable range. The US is not.

click for ginormous charts
Top Marginal Rates
Source: IMF

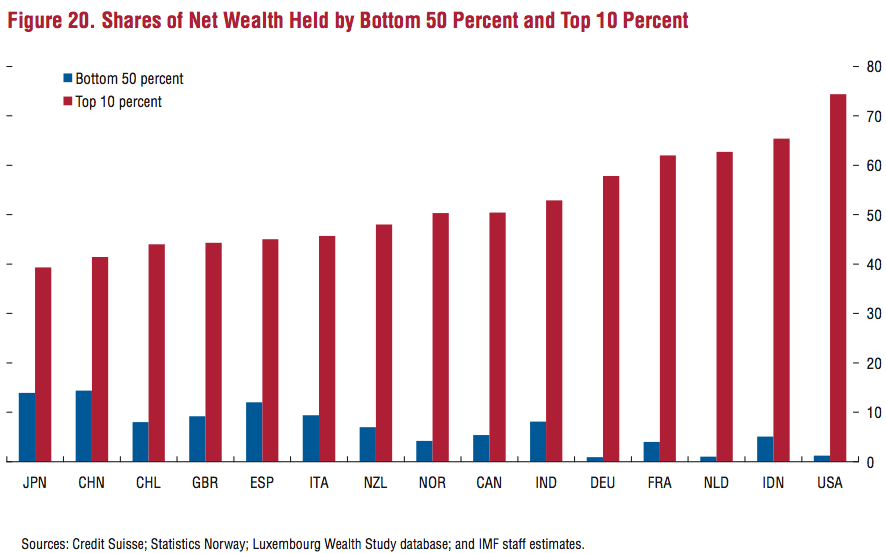
Not coincidentally, when we look at shares of Net Wealth held by the bottom 50% of he population versus the top 10%, the United States is off the scale. We are the most unequal nation in the world.

Shares of Net Wealth
Source: IMF

The inescapable conclusion presented to us by this data is that our tax policy is responsible for both the world’s greatest inequality among developed nations, and our ongoing deficits.

If you have a better explanation for our current conditions, or the net results of our tax policies, I would love to hear it.

Source:
Fiscal Monitor Taxing Times
World Economic and Financial Surveys
IMF October 2013
http://www.imf.org/external/pubs/ft/fm/2013/02/fmindex.htm

Did Monetary Policy Cause the Recovery? – John Hussman. A very nice demolition of our monetary policy charade for Janet Yellen to consider. Let’s hope she has the guts to make some heads roll [i.e., to bring back honest accounting].

[…] To address this question, a proper understanding of the credit crisis is essential. Much of the present faith in monetary policy derives from the belief that it was the central factor in ending the banking crisis during what is often called the Great Recession. On careful analysis, however, the clearest and most immediate event that ended the banking crisis was not monetary policy, but the abandonment of mark-to-market accounting by the Financial Accounting Standards Board on March 16, 2009, in response to Congressional pressure by the House Committee on Financial Services onMarch 12, 2009. The change to the accounting rule FAS 157 removed the risk of widespread bank insolvency by eliminating the need for banks to make their losses transparent. No mark-to-market losses, no need for added capital, no need for regulatory intervention, recievership, or even bailouts. Misattributing the recovery to monetary policy has contributed to a faith in its effectiveness that cannot even withstand scrutiny of the 2000-2002 and 2007-2009 recessions, and the accompanying market plunges. This faith is already wavering, but the loss of this faith will be one of the most painful aspects of the completion of the present market cycle. […]

The simple fact is that the belief in direct, reliable links between monetary policy and the economy - and even with the stock market - is contrary to the lessons from a century of history. Among the many things that are demonstrably nottrue - and can be demonstrated to be untrue even with simple scatterplots - are the notions that inflation and unemployment are negatively related over time (the actual correlation is close to zero and slightly positive), that higher inflation results in lower subsequent unemployment (the actual correlation is positive), that higher monetary growth results in subsequent employment gains (the correlation is almost exactly zero), and a wide range of similarly popular variants. Even "expectations augmented" variants turn out to be useless. Examining historical evidence would be a useful exercise for Econ 101 students, who gain an unrealistic sense of cause and effect as the result of studying diagrams instead of data.

Friday, January 11, 2013

Another comment on Modern Monetary Theory

I continue to believe that the attraction of MMT to modern liberals like Jamie Galbraith and Warren Mosler (I consider myself a classical liberal) is that something like the trillion dollar coin enables an end run around the fecally impacted banking system to get an inflation going, when the debt-deflationary forces in the private economy and banking system—in which, it is true to say, all money is debt—are overwhelming even Helicopter Ben’s attempts to get a nice, mild inflation going.

It might work, especially if accompanied by starting (or expanding) a significant war effort, but of course the fundamental problem is the Fed, especially since that great conservative Richard Nixon took us off the gold standard (he also opened the door for that gi

Source:  Rogoff via businessinsider.com

The fact an establishment economist like Rogoff could present such material at the annual economics meetings, and that Krugman and the White House won’t issue non-denial denials that they are taking this seriously, tells me that we are very close to the unraveling of the Bretton Woods II monetary system, and possibly to some fundamental change in the way the Fed operates.  There are rumors of a new monetary system in the works, and the way this is being sent out suggests to me it’s a trial balloon—so that they can come up with “the better idea.”

I just can’t imagine that the better idea will not involve some attempt to accelerate inflation, given the grip of the creditors on the sovereigns, and aggregate inability to clear bad debt out of the system.

Europe is showing the world what austerity looks like, and it ain’t pretty.

Sunday, January 6, 2013

Tinder in place

Via: Debka.com

With a buildup of 16 Russian warships carrying thousands of marines on the Syrian coast “to deter the West from deploying ground forces in Syria,” Syrian Bashar Assad could afford to brazen it out in his first public speech in seven months. Speaking at the Damascus opera house, Sunday, Jan. 6, Assad said Syria no longer takes dictation from anyone and called on Syrian citizens to defend the country against “a war fought by only a handful of Syrians and many foreigners.”

He rejected dialogue with the opposition which he referred to as “puppets fabricated by the West.”


Tuesday, September 11, 2012

Graph of the day

Via:  arxiv.org/abs/1108.2455: The Food Crises and Political Instability in North Africa and the Middle East

Via:  MIT Technology Review

What causes riots? That's not a question you would expect to have a simple answer.

But today, Marco Lagi and buddies at the New England Complex Systems Institute in Cambridge, say they've found a single factor that seems to trigger riots around the world.

This single factor is the price of food. Lagi and co say that when it rises above a certain threshold, social unrest sweeps the planet.

The evidence comes from two sources. The first is data gathered by the United Nations that plots the price of food against time, the so-called food price index of the Food and Agriculture Organisation of the UN. The second is the date of riots around the world, whatever their cause. Both these sources are plotted on the same graph above.

This clearly seems to show that when the food price index rises above a certain threshold, the result is trouble around the world.

This isn't rocket science. It stands to reason that people become desperate when food is unobtainable. It's often said that any society is three square meals from anarchy.

But what's interesting about this analysis is that Lagi and co say that high food prices don't necessarily trigger riots themselves, they simply create the conditions in which social unrest can flourish. "These observations are consistent with a hypothesis that high global food prices are a precipitating condition for social unrest," say Lagi and co.

In other words, high food prices lead to a kind of tipping point when almost anything can trigger a riot, like a lighted match in a dry forest.

On 13 December last year, the group wrote to the US government pointing out that global food prices were about to cross the threshold they had identified. Four days later, Mohamed Bouazizi set himself on fire in Tunisia in protest at government policies, an event that triggered a wave of social unrest that continues to spread throughout the middle east today.

That leads to an obvious thought. If high food prices condition the world for social unrest, then reducing the prices should stabilise the planet.

But what can be done to reverse the increases. Lagi and co say that two main factors have driven the increase in the food price index. The first is traders speculating on the price of food, a problem that has been exacerbated in recent years by the deregulation of the commodities markets and the removal of trading limits for buyers and sellers.

The second is the conversion of corn into ethanol, a practice directly encouraged by subsidies.

Those are both factors that the western world and the US in particular could change.

Today, the food price index remains above the threshold but the long term trend is still below. But it is rising. Lagi and co say that if the trend continues, the index is likely to cross the threshold in August 2013.

If their model has the predictive power they suggest, when that happens, the world will become a tinderbox waiting for a match.

Wednesday, August 1, 2012

Pictures of monetary instability

Via:  FT

In line with my thesis that the coming years will feature a degree of monetary instability unprecedented in human history, beginning with ubiquitous negative real rates that are the scourge of banks….

Negative rates as a precursor to the death of banking

Posted by Izabella Kaminska on Jul 31 16:02.

FT Alphaville has presented its case on negative rates and zero deposit rates here andhere (amongst other places).

What we believe is that rather than stimulating the lending market — and the economy along with it — such a rate policy could have a disastrous impact on collateral markets and money market funds, not to mention the net interest income of lending institutions. All of which could unleash a protracted deflationary spiral.

The move could also presage the death of banks and lending institutions completely. […]

Check out the pictures of some major yield curves around the world:

UK:

Australia:

Switzerland:

If you buy the argument that central banks this far gone down the path of excessive accommodation lo this past forty years have only one option left to serve their masters, the fiscal authorities and the creditors, inflate or die, then keep in mind that historically, the quickest way to get an inflation going is to start a big war.

I am beginning to see why Charles Nenner says there is no free will—yet I retain hope that there is.

Tuesday, February 28, 2012

How long can rates stay low?

The last time the U.S. was in ZIRP—Zero Interest Rate Policy—was in the Great Depression, and short rates stayed low for a surprisingly long time, from 1934 to 1947, with the much-maligned blip in 1937 being blamed for the recession of 1937-38 by some, while others point to fiscal tightening—together it’s a knock-out punch.  Until 1942 three-month T-bill rates were like today’s, ten or twenty basis points, until 1942 when they were pegged at 38bps for the duration of the war.

FRED Graph

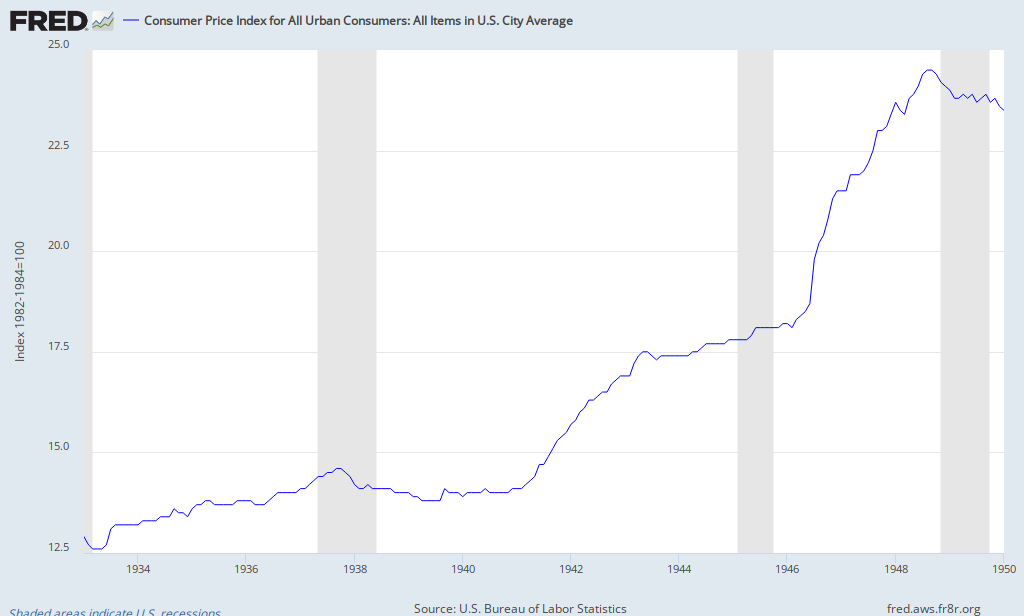
That’s eight years with rates mostly below 20bps, and 14 years if you call 38bps low.  Here’s what was going on with inflation:

FRED Graph

Price controls were used during World War II (and later the Korean War, and later during the early ‘Seventies) to try to control inflation that accelerated after the war until monetary tightening brought on the recession of 1949.

We entered ZIRP at the end of 2008.  It’s only been a little over three years.  It could be a long ride.

Housing bottom? You’ve got to be kidding

With all the divination of the graphical tea leaves going on—are we at a bottom, or bouncing along the bottom, or will we go lower?  gasp!—it is worth remembering that houses are bought “on time,” and that most people buy all the house they can (even if they have to put down 20 percent)—and that interest rates are currently at historical lows, so that a further decline is just about baked in, especially given current price weakness.

If mortgage rates rise from 4 percent to 6 percent, the payment on a 30-year mortgage goes up 25 percent.  People aren’t going to be able to afford the same price house.  Here are empirical results for the Case-Shiller 10 City and US indices showing the inverse relationship between house prices and interest rates very clearly:

image

image

Add to this problem—and interest rates will go up again sometime, and if they go up in a galloping inflation we will see a complete collapse of the housing market, as banks and their regulators will not permit another bubble to form quickly—although one will form even with 20 percent down given enough time—and because interest rates will rise more quickly than house prices, and because people are becoming just as afraid of the housing market as they are of the stock market.

You say we’re near a housing bottom?  You’ve got to be kidding!

Saturday, January 28, 2012

Bretton Woods super-nova reprise

My central thesis is the current debt super-cycle will end in a race to inflate and cause currency depreciation by all the world’s central banks that foolishly adopted the Western fractional reserve monetary system with the U.S. greenback as its reserve currency, that was at first pegged to gold up till Richard Nixon’s abandonment of the gold peg in 1971.

What a conservative, Nixon.  Wage and price controls, abandonment of any shred of monetary discipline for the entire world.. but he went to China…. What a dude!

Just as virtually every American must go up a learning curve with credit cards—many marriages have a “credit card moment” where the cards get cut up and a new fiscal regime begins—so the entire world has traveled down the borrow-and-spend-because-we’re-worth-it path that has led to the current mountain of debt on the shoulders of the global Sisyphus, as the world tries to push the boulder back up to the mountaintop.

The world is now on the steepest upward slope of the credit learning curve.

But central banks are not like people.  Central banks print money.  Too much money chasing too few goods equals inflation.  Inflation equals reduced purchasing power, and hence reduced real debt burdens.  This is all undisputed by all brands of economists.  The disagreement is whether the central banks, who have stated publicly that a little more inflation would definitely be a good thing, can get an inflation going in a liquidity trap, where, because everyone already has too much debt, they don’t want any more.

Ah, but even as all fractional reserve fiat money is technically credit debt, it is also a medium of exchange used for transactions for goods and services, including labor.

If an inflation is a sustained rise in the general price level, a working definition that should be acceptable here, then it is a labor market phenomenon as well as a monetary phenomenon.  I’ve gone so far as to say that “Inflation is always and everywhere a labor market phenomenon—a wage-price spiral—accommodated by monetary policy.”

So to get an inflation going in an admittedly quite deflationary environment (deflation is what happens when asset values supported only by bad debts on the liability side of the social balance sheet collapse as the badness of the liabilities is recognized, however slowly) you need to have some prices rise, perhaps because of a supply shock, and then to have businesses accommodate the however feeble demands for increased compensation to maintain real wages, a move that businesses would make only out of a renascent sense of social responsibility to labor and out of the record share of GDP they have garnered to capital in recent years. 

Then it is simply a matter of supply costs maybe going up a little more, maybe as the result of a different supply shock from a different sector—say the first was oil, as a war gets going in the Middle East, and the second is due to crop failures around the world because of a summer drought—and rather than send their economies into depression, the central bankers will accommodate as necessary, although with the level of excess reserves available in the banking system it may not take much accommodation in the initial phases of the new inflation.

And so a wage-price spiral is born that can support a sustained rise in the price level that can reduce the real value of outstanding debts.

The nation that gets the inflation going first wins in the super-nova of Bretton Woods.  Everybody’s got too much debt (in the Western world) and the first nation to depreciate its currency and the value of its debt picks up exports while paying down debt.  They reach the top of the mountain first.

And as I pointed out recently, the quickest way to get an inflation going—and I would maintain this applies even in a deflationary environment—is via the supply shortages and rationing that accompany a big hot war.

Hence I believe Daddy Warbucks and his military-industrial complex friends are pushing the United States toward war as quickly as possible.

But what will happen when the entire Western world rushes to follow, as I don’t believe the Europeans will be able to avoid the temptation in the event?

Collapse of the world financial system is a distinct possibility.  A galloping inflation or hyperinflation across the Western world would make international transactions highly uncertain.  Barter arrangements might be made for big ticket items like energy (already happening between Iran and China).

In the U.S. inflation and a return to positive real interest rates would at least kill the carry trades that have enriched the financial elite for a decade or more, would pull many homeowners into positive equity, and would most benefit those who locked in to super low rate financing as they leverage the funds into commodities.

When this will happen is anyone’s guess.  There are credible predictions by Charles Nenner, John Robb and others that a major war will begin this year or next.

China will implode into authoritarianism as their bifurcated economy tanks.  There will be no war with China this time, except for a possible skirmish or two in the Caucasus.  

The neocons, including Obama, who faces reelection, for which a war is always a useful ruse, will argue that we need to occupy the Middle East to assure supplies of “our” oil.  Israel will encourage the U.S. to decimate the populations of several Middle Eastern countries that it considers a threat to its survival.

All across America, Americans are transfixed by a Republican primary race that rivals the tackiest daytime soap opera for lurid content and lowbrow appeal.  Keep that TV on so you don’t have to think!

All the talk about taking America back will be put on hold for a moment as Chaos rears its ugly head and the last vestige of normality in the economy vanishes.

But then, as the world enters a period of Total Uncertainty, there will be an opportunity for revolutionary change.  For an amendment to the Constitution to declare that corporations are not people.  For progressive taxation that recognizes that the people sitting at the top of our corporations are not doing all the work, and that returns after-tax income distributions to levels found in healthy societies (cf. Wilkinson).

Because if we’ve learned anything in the years since Hank Paulson announced that if he didn’t get his way, a depression would start on Monday and martial law would need to be declared—if we’ve learned anything, it’s that the false god of Econ has lied to us lo these three or four decades.  Lied abjectly.  And the psychologists and epidemiologists, whose best work is ignored by behavioral economist whores running investment management businesses, have shown us that happiness and human welfare do not increase with GDP in any meaningful way, that more income above a level that satisfies some basic human wants and needs does not make us better off, but that what makes us happy and vibrant and alive and long-lived and healthy is living in an interconnected, more-equal-than-now human community, with a sense of interconnectedness and a lack of the chronic status insults, social stratification and isolation and personal degradation that accompany life in latter day banana republics like the United States.

The last world war produced the most pronounced leveling of the American income distribution in recorded history (cf. Income, inequality, debt, crisis and depressions).  There is a secret hope within the Beltway, methinks, that we can pull off the same trick again with the right conflict, started by the right false flag incident.

But the public is smarter than it has ever been.  IQ scores have been rising.  Information is instantly available around the world.  It’s hard to create a bogey man today.  The people know all the Hollywood tricks.  And they’re sick of war.

It’s no accident that folks in the U.S. military services overwhelmingly support Ron Paul.

So the next time the world enters a historical moment of Total Uncertainty, let’s be ready to use it to get what the 99 percent want, starting with a Constitutional amendment that corporations are not people, and from there on to a clean up of the laws that should govern this land, that the 1 percent who currently live above them may rejoin the human fold.

The readiness is all.

Peace.

Thursday, July 28, 2011

Competitive inflation or deflation?

It has been widely asserted that the only way for the Western world out of its debt problems is competitive inflation.  But it is hard to get an inflation going during a debt deflation.  If we are on the verge of a deflation, what will the competition involve?

Deflation is the reverse of inflation.  Therefore, if winning involved having the fastest inflation rate in competitive inflation, then the country with the slowest fall in prices should win, as, just like inflation, it will relatively reduce the value of its debt the best.

Europe stands a pretty good chance of deflation if the EU fails and debt loads collapse economies (see Simon Johnson’s analysis here).  Europe’s debt problems are worse than America’s.

And, as always in deflations, commodities fall, U.S. Treasury interest rates fall, risk premia rise, stocks fall, and the vastly neglected real economy tanks yet again.  More people lose their jobs, and more children go hungry in the emerging banana republics of the developed world.

Then a bigger war and the big inflation begin, if history rhymes.

Friday, April 1, 2011

No rate increase in sight

Dent’s unoriginal take is that housing will behave just like Japan’s did after peaking in 1990.  Prices won’t come back for a couple of decades.

If we get a major war in the next three years as Charles Nenner and Gerald Celente expect, we will have what I call “stagflationary deflation”:  sectoral supply-shock price increases that further squeeze nominally unchanging household budgets (at least for the bottom ninety percent).  Consumption at seventy percent of GDP is unsustainable, and what is taken out of consumption would be replaced with war spending.  Consumption would be effectively if not administratively rationed.

“Inflation is always and everywhere a labor market phenomenon accommodated by loose monetary policies.”

Monday, March 14, 2011

Comment on MMT approach to sectoral balances

Yves links to an MMT-oriented site (www.macrobusiness.com) this morning that delves into the issue of “sectoral balances,” which are related to the national income and product account identities.  I find that any argument based on an identity is weak to begin with, but the conclusions forced upon this identity by the blogger are not necessary.  Here’s the basic idea:

Sectoral Balances 101

I have written before on this blog about the idea of sectoral balances (as has my fellow blogger Delusional Economics). As you may recall, this is a basic accounting identity which states that in any economy over a fixed period of time, the following must hold true:

Private Sector Balance + Government Sector Balance – Current Account Balance = 0

  • The private sector balance is the excess of savings over expenditure for businesses and households.
  • The government sector balance is government tax revenues less spending.
  • And the current account balance is (in simplified terms) a country’s exports less its imports.

I buy this.  Fact is the U.S. has been running both private and public sector deficits for a long time.  By one estimate I heard at a conference recently, all but one year of positive real GDP growth in the prior decade would not have occurred without home mortgage equity extraction.  And we all know the government has busted its budget royally, accelerating under Bush II and Obama especially.

One thing about identities is that they don’t really capture real economic forces.  Say we wanted to balance the government’s budget.  Rewriting, we have

                 (-)          +                    (-)                =               (-)
Private Sector Balance + Government Sector Balance = Current Account Balance

So if we left the private sector balance alone, all we have to do is reduce the current account balance!  Then we’d only be borrowing to support our private over-consumption!

See how misleading this is?  The problem with balancing the budget in the near term is that it puts the nail in the coffin of effective demand.  Government workers are fired across the land.  Retail sales collapse.  Unemployment shoots up.  Confidence collapses, multiplier and multiplier-accelerator effects proliferate, private investment evaporates, and we are in a more serious depression than we’re in now.

The MMT solution, of course, is to continue printing our “monopoly money” (really!) until inflation becomes a problem, which they say is far away.  This is a Ponzi scheme, as the dollar is the reserve currency.  We are exporting our fiscal failures.  Carry trade excesses are inevitable, as is major blowback from the rest of the world when they get tired of holding our fiscal feces.  War-induced inflation is more probable in the near term.

The one inescapable implication of the identity above is that when as a nation you’re spending more than you make, you must borrow from the rest of the world.  To remedy that requires an across-the-board belt tightening.

Given that, the only long-run solution is to rebalance domestic demand to avoid the country splitting apart (see www.theburningplatform.com on “the gathering storm”).  In the intermediate term this will require mitigating extreme income inequality with more progressive taxation; a poverty level dole for families displaced by the depression offered as workfare; a decent education for the kids; and an extension of Medicaid in lieu of the ridiculous “solution” forced on the Democrats by the health insurance industry.  Otherwise we will destroy our most valuable asset, our human capital. 

What we have now is socialism for the rich.  Let’s call a spade a spade.  The banking bailouts were the largest transfer of wealth from working taxpayers to the rich in the history of the world, as Barry Ritholtz (www.ritholtz.com) never tires of pointing out.  “Winner take all” compensation schemes are everywhere.  The rich have manipulated virtually every aspect of taxation and corporate governance to their benefit.  No nation is better than its treatment of its poor.  (A deeper question:  Does the nation-state still have any power, when multinational corporations run the world?)  America ignores the lessons of history at its gravest peril.

What we need is a little more “socialism” for the rest of America.  Or, as Adam Smith and I would prefer, a return to a capitalism within a framework of upgraded “moral sentiments” on the part of all Americans.

Cain asked the question, “Am I my brother’s keeper?” 

Do you know the answer?

Tuesday, February 22, 2011

Inflation, hyperinflation or deflation next?

By the measure of final sales to domestic purchasers, domestic aggregate demand has not recovered to 2007 levels; the chart shows final sales to domestic purchasers deflated by the personal consumption expenditures deflator:

image

Inflation is running ahead of official estimates, according to credible sources cited here:

What happens next is deflationary stagflation: food and energy prices rise, consumer purchasing power takes a hit, and the constraints on the flow of income contribute to further declines in house prices and other consumable assets.

Overall, the intermediate term—debt deflation, asset price declines, exacerbated by supply shocks to items with relatively inelastic demand.

To get a real wage-price spiral going you have to actually pay people enough to cover inflation and then some, and right now the movement in the labor market is toward bashing labor whenever and wherever possible. This is Bernanke’s and every liberal economist’s wet dream, that we get to inflate our way out of our debt once again, just like the old days.

The difference this time is the debt mountain on our backs. When debts don’t get repaid—because of income insufficiency—asset values fall.

image

The wild card is war. Throughout history, wars have been associated with inflation, and with a larger role for government in the economy. The mainstream parties, Republican and Democrat, have supported all the recent wars slavishly. Only Ron Paul and the Tea Party oppose more war. Whether they really mean it is a mystery to me. There is a lot of unfortunate baggage that goes along with the Tea Party, but at this time, they are the only movement willing to take on the military-industrial complex and provide real change—for which the American public is hungry, as Obama demonstrated. Whether they could actually accomplish anything given the way Congress works is doubtful to me. It would take a sweeping repudiation of the mainstream parties, and the Tea Party so far seems to be traditional Republicanism in sheep’s clothing (financed by the Koch brothers, etc.).

The system is currently dysfunctional. We are entering a crisis episode in which new rules of the game will emerge, one way or another. I believe in peaceful protest. Egypt was inspiring in this regard.

Peace.


See also You Want Inflation? Here's How To Get It

Monday, February 14, 2011

Comment on “modern monetary theory”

Inspired by Lincoln’s printing of fiat money to finance the Civil War, “modern monetary theory” posits that deficits don’t matter, that money is as money does, and that we should just print more money to get out of our present debt hole.  I haven’t addressed MMT before (except to dismiss it once, as I recall, as just another ruse to inflate our way out of our debt) because I considered it beneath the level of serious discourse, but Jesse has a nice demolition of it here, that I would like to add to.

Indeed, MMT is just another ruse to inflate our way out of our debt, which in the context of a fiat money world, Bretton Woods II, requires that our currency depreciate against others, but not so much that people refuse to accept it any more.  Money is what people accept as money, and if folks stop accepting the dollar—whether as reserve currency or not—then the U.S. is hosed.  Our banana republic status becomes official.

What I would like to add to Jesse’s analysis is the hidden truculent aspect of MMT.  In the context of a declining, bankrupt empire whose denarius is still widely accepted, an empire threatened by “barbarians” at its borders and dissent within, the best way to keep your denarius viable is to sow chaos across the rest of the world.

The Bretton Woods II super-nova, as I have called it, is just beginning to flame out.  The world-wide housing bubble was not created by Wall Street but by Washington forty years ago when the world went on Bretton Woods II.  Sure, Wall Street piled on and sold the rest of the world a bunch of toxic assets, to do their part to support the empire.

But should democratic reform spread—should the Europeans work out their problems, should China successfully reign in its bubble—should there become a viable alternative to the dollar, and the oil price rise sharply in dollars—there will continue to be strong incentive for the U.S. empire to defend its currency by sowing chaos throughout the world.

Wars have always been the best way to stimulate inflation.  And “modern monetary theory,” which disingenuously offers the old ruse of inflating one’s way out of debt, implicitly invites inflation and war.

Thursday, June 24, 2010

Mish slashes Krugman

http://globaleconomicanalysis.blogspot.com/2010/06/krugman-suffers-foot-in-mouth-disease.html

I need to say (again) that our current problem is not fundamentally one of insufficient aggregate demand or aggregate output, but of its distribution.  Our social contract is broken, our income and wealth distributions are obscene.  There is enough to go around, we are richer than we were twenty years ago, it just isn’t going around.

The Germans and the EU states in general have (1) state subsidized health care for all (2) a livable dole for the unemployed, and (3) a memory only a few generations old of hyperinflation.

Once they decide to discipline their unions, the EU countries will be able to weather a fiscal tightening without catastrophe.  They will hunker down together and drink wine.

The reason the Feds have been paying for the states’ unemployment insurance claims in the US (to the tune of a reported $10 billion a month) is because we don’t have a livable dole, or health care for all, and millions of families, many with children, are entering a humanitarian catastrophe right under the noses of the “sovereign individuals,” Tea Partiers, and members of the Party of “No,” the Republicans.

Krugman, a New Yorker unable to separate himself from the local zeitgeist, is effectively a mouthpiece for a Wall Street that is salivating over the opportunity to lever up with free money from the Fed for a hyperinflation and make a really big killing.  Perhaps this time they can evict the entire bottom 99 percent of the income distribution from their houses, or at least reduce them to penury and an appropriate attitude of servitude.

“Let them live on the streets, it’s a free country.”  The Peter Schiff platform.

.     .     .

Post script:

But I'd also like to point out that large financial centers in certain cities around the planet are certainly going to kill millions of us by destroying our social safety networks in the name of their imaginary financial efficiency. You're a thousand times more likely to die because of what some urban banker did in 2008 than from what some Afghan-based terrorist did in 2001. *Financiers live in small, panicky urban cloisters, severely detached from the rest of mankind. They are living today in rich-guy ghetto cults. They are truly dangerous to our well-being, and they are getting worse and more extremist, not better and more reasonable. You're not gonna realize this havoc till you see your elderly Mom coughing in an emergency ward, but she's going there for a reason.

--Bruce Sterling, in boingboing.com


The Global Political Awakening and the New World Order

Thursday, January 28, 2010

“Sell? To whom?”

Via:  The Fed's Anti-Inflation Exit Strategy Will Fail – Allan Meltzer in the WSJ

Prof. Meltzer demeans himself by even addressing the Fed’s ridiculous proposition that by paying interest on reserves the Fed can control excess reserves.  Where is the reserves interest going to come from?  This is just another underhanded way to try to recapitalize the bad banks (not all banks are insolvent).

Meltzer instead suggests the Fed use the traditional method of selling securities to suck in high-powered money.  But what are they going to sell, and to whom (the “Wall Street question”)?  The Fed has taken in untold and literally unknown amounts of garbage as if it were worth being reserves—they won’t even tell us what it is or how much of it has already charged off!

If and when inflation becomes a problem (when the next Big War gets going) the Fed won’t have the balls to reign in anything, would be my guess.  And we know the Whole Sick Crew of neoclassical economic advisors to the President are on record as welcoming an inflation to “lower the debt load.”

In the meantime the only thing that will restore a healthy middle class to America is an explicitly redistributionist rebalancing of aggregate demand.  Let the ruling class that has engineered the economy and the tax system to its own benefit for the past generation start to pay its own bills—especially the gigantic Wall Street bailouts, the largest transfer of wealth from ordinary Americans to the wealthy in history. 

[I hate to admit it, but a rebalancing of aggregate demand that put more money in the hands of the middle class would also increase the odds of a “benign” mild wage-price inflation getting going.  Combine this with a concerted effort to get big American corporations to knock their preening executives off their pedestals—who strut through the halls wearing expressions that say, “We are gods, oh ye puny cube-dwellers!  Do not think that you are even the same species as we!  You will never join our club!”—and get pay ratios in America back toward something that doesn’t cause gagging, and the economy might just pick up steam….]

Raise marginal tax rates on the super-rich to where they were in the 1950s (see this), the last time the federal debt load was this high.

I called my Senators today and told them to dump Bernanke.

P.S.  The Fed always has reserve requirements to reign in excess reserves.

P.P.S.  If the Fed had not bailed out the banks, and instead had provided unlimited deposit protection, what would have happened?  There would be a large amount of high-powered money in the hands of the public rather than in the banks.  The public could have made runs on as many banks as they liked, and the banks that lost their deposit base failed, and there would have been no massive wealth transfer to the investors in the failed banks—but the executives of the banks that levered up irresponsibly would be out of work, instead of cracking jokes to Congress about financial crises being something that come around every seven years, and paying themselves record bonuses.  Would this have been inflationary?  No.  People are reducing their marginal propensity to consumer, and increasing precautionary demand for money.  When things calmed down, they just would have put the money back in a bank.

Tuesday, January 26, 2010

The next bubble?

Cf.:  The Total Debt Relative to GDP Trumps Everything Else – Comstock Funds

Comstock has published Ned Davis’s charts on total debt/GDP for years.  They wonder why no one among the financial pundit (i.e., dunce) class can see the elephant in the room.

Barron's magazine printed the first part of its annual Roundtable discussion of 2010 this past week.  We noticed that many of the participants were very concerned about the debt (mostly government debt while we think total debt is a much more useful metric).  Marc Faber, in fact, talked about a 7,000 word New York Times article by Professor Paul Krugman.  He stated that the article "How Did Economists Get It So Wrong?" never mentioned that excessive credit growth or leverage was the cause of monetary instability and brought about the financial crisis.  Bill Gross stated that by lowering interest rates we promote consumption instead of manufacturing.  Central bankers were forced to respond with liquidity to a problem that developed over the past 25 years.  There was more discussion of credit growth (another way to say debt growth) in the macro analysis that is always presented in the first part of the three Barron's articles of the Roundtable.  The amazing thing to us is that most of the roundtable participants understand the same problems we talk about almost every single week, yet are mostly very positive on the market for 2010. 

It seems that most of the roundtable participants understand the debt problem we have been talking about for the past 14 years. The worst period of the debt explosion started with the outrageous internet bubble in the late 1990s, continuing through the correction in the internet bubble, then the housing bubble which should have been obvious to everyone (even the Fed) and then the financial crisis of 2008.  We are astounded that we have the potential for another bubble in the stock market now.  We expected the rebound from a much oversold market in March of 2009, but not a 70% rebound from the lows.  We don't believe it is possible to fool the investors in the US stock market one more time. Especially this close to the 2003-2007 and 1996-2000 bubbles. 

They expect competitive devaluation as I do in what I call the “supernova of Bretton Woods.”  See the pdf on “The Cycle of Deflation.”  However, I am more concerned that desperate governments will resort to war, a tried and true inflation-starter, to counter currency appreciation due to deflation.  You’ve got to have inflation to devalue your currency under floating rates.

Anyway, their bearish view of the US stock market matches mine, and raises the question:  What will Ben’s (or whoever’s) next [asset] bubble be, the chances for wage-price spiral being about nil as the jackboot comes down on the labor market Big Time?

I am going to guess it’s Oil.  Goes hand-in-hand with geopolitical instability.  But as I wrote in the last “animal spirits” update, we’re likely to experience a period of eerie calm (and further deflationary real estate wreckage as the next wave of resets hits) before any wage-price inflation happens.

This is not to say that there is no inflation.  Anyone who buys gas or goes to a grocery store can see it in their monthly budget.

Total Debt (Public & Private) Relative to GDP
The Cycle of Deflation